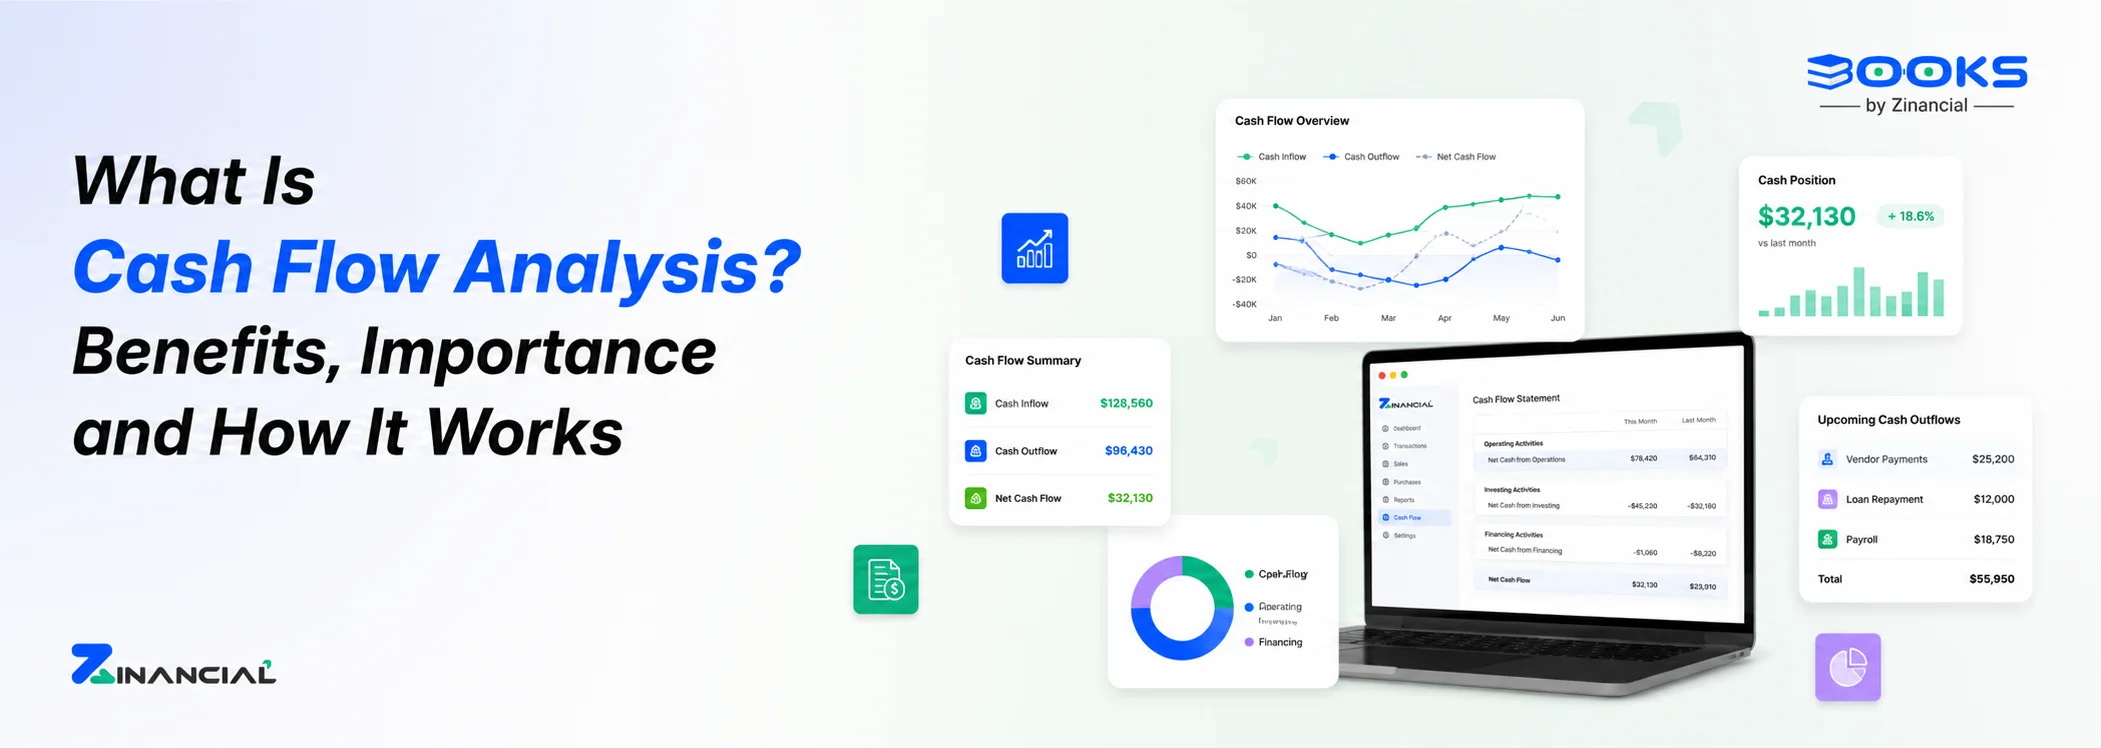
You can perform cash flow analysis by reviewing cash inflows and outflows, comparing cash movements across periods, and identifying the factors that are affecting your cash position.
Follow these steps:
Step 1. Collect Your Cash Flow Data
Start with reliable financial records for the period you want to analyze. Use your cash flow statement, bank records, accounting system, and other relevant financial data.
Separate the information into major categories such as operating activities, investing activities, and financing activities.
Step 2. Review Cash Inflows
Identify where the business’s cash comes from. Common sources include:
- Customer payments
- Sales receipts
- Loans and financing
- Investment income
- Owner or investor contributions
- Asset sales
Look for significant changes in the amount or timing of cash received.
Step 3. Review Cash Outflows
Next, examine where the business is spending cash. Consider operating expenses, supplier payments, payroll, taxes, debt repayments, asset purchases, and other significant payments.
Look for expenses that have increased unexpectedly or payments that are putting pressure on available cash.
Step 4. Calculate Net Cash Flow
Calculate the difference between total cash inflows and total cash outflows:
Net Cash Flow = Total Cash Inflows − Total Cash Outflows
A positive result means more cash entered the business than left it during the period. A negative result means the business paid out more cash than it received.
However, one period should not be viewed in isolation. Review the result alongside previous periods and the business’s available cash balance.
Step 5. Compare Cash Flow Across Periods
Compare cash movements across weeks, months, quarters, or years to identify trends.
Look for patterns such as:
- Increasing or declining customer collections
- Rising operating expenses
- Seasonal changes in cash flow
- Increasing debt payments
- Changes in investment spending
- Persistent negative operating cash flow
Trend analysis can help distinguish a temporary change from a recurring cash flow problem.
Step 6. Investigate Significant Changes
Once you identify a significant change, determine what caused it.
For example, a decline in cash may result from slower customer payments, higher inventory purchases, a large equipment investment, or increased operating costs.
Understanding the cause is more useful than simply identifying that cash decreased.
Step 7. Assess the Business’s Cash Position
Finally, consider whether the current cash position is sufficient to support upcoming obligations and business plans.
Review available cash alongside upcoming payments, working capital requirements, debt obligations, and expected customer collections.
The purpose of cash flow analysis is not simply to calculate how much cash changed. It is to understand what caused the change, whether the pattern is sustainable, and what action the business may need to take.